
Multi-Family & Commercial Bridge Lending Programs
Multi-family and commercial loans provide short-term capital for assets that need to move forward—not wait for rigid approval cycles.
Rates from
9.50%
Loan from
$500K – $10M
Terms from
12-36 months
Up to
70% LTC
Funding Your Multi-Family & Commercial Bridge Loan
Multifamily and mixed-use projects don’t fail because the opportunity disappears. They slow down when financing can’t adapt to the timing, complexity, or needs of the project.
Insignia Capital Corp provides bridge financing for multifamily and mixed-use properties, including acquisitions, construction completion, value-add projects, lease-up, stabilization, and other transitional situations where conventional financing may not fit.
Insignia Capital Corp’s experienced credit team is focused on providing flexible, execution-driven capital that helps experienced real estate investors and developers move a project from its current stage toward stabilization, sale, or permanent financing.
Other commercial real estate opportunities are considered on a case-by-case basis.
Loan Purpose
Terms
Property Type
Multi-family, mixed use & commercial
Loan amounts
$500K – $10M
LTV
80%
LTC
70%
LTARV up to
75%
Rates from
9.50%
Points
1.00% to 3.50%
Fees from
$1,995
Payments
Interest-only
Term
12-36 month
Prepay penalty
None or negotiable
Minimum credit score
640
Borrower entity required
No
Experience
Better pricing for pros

Case Study
Multi-Family and Commercial
Funded 25-Unit Multi-Family Bridge Loan
A seasoned borrower approached Insignia Capital Corp to refinance a bridge loan on a 25-unit apartment building in Koreatown. The borrower, an experienced multi-family investor with over 1,000 units, needed to reduce exposure to riskier bridge loans due to rising interest rates in 2023.
The Solution:
Insignia Capital Corp facilitated a timely refinance before the loan’s maturity. Leveraging direct access to a pension fund, we secured a $6M bridge loan at 77% LTV, with a two-year term, a 10.95% interest rate, and no prepayment penalty. The borrower needed a two-year window to complete additional ADUs on the property, enabling a subsequent transition to a traditional loan refinance.
Despite a tight lending environment, Insignia’s expertise provided more competitive terms and greater flexibility for the borrower.
$6M
Loan
24
Month Terms
77%
Loan to Value
10.95%
Rate
Recently Funded Transactions
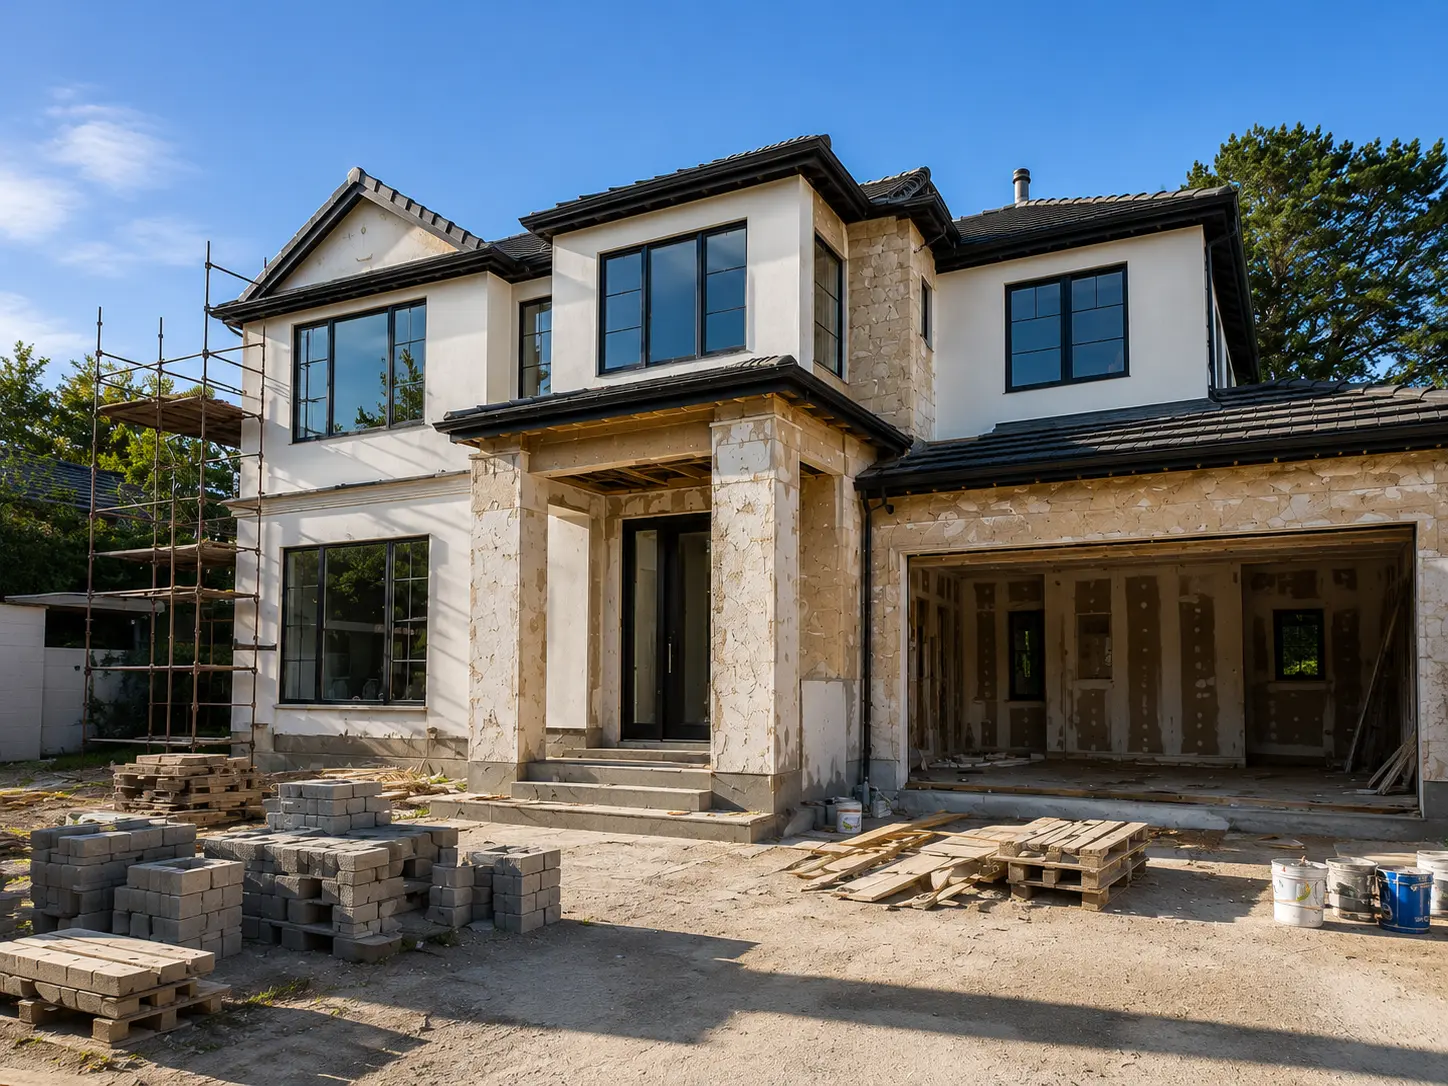
$4.95M
Single-Family Bridge Loan
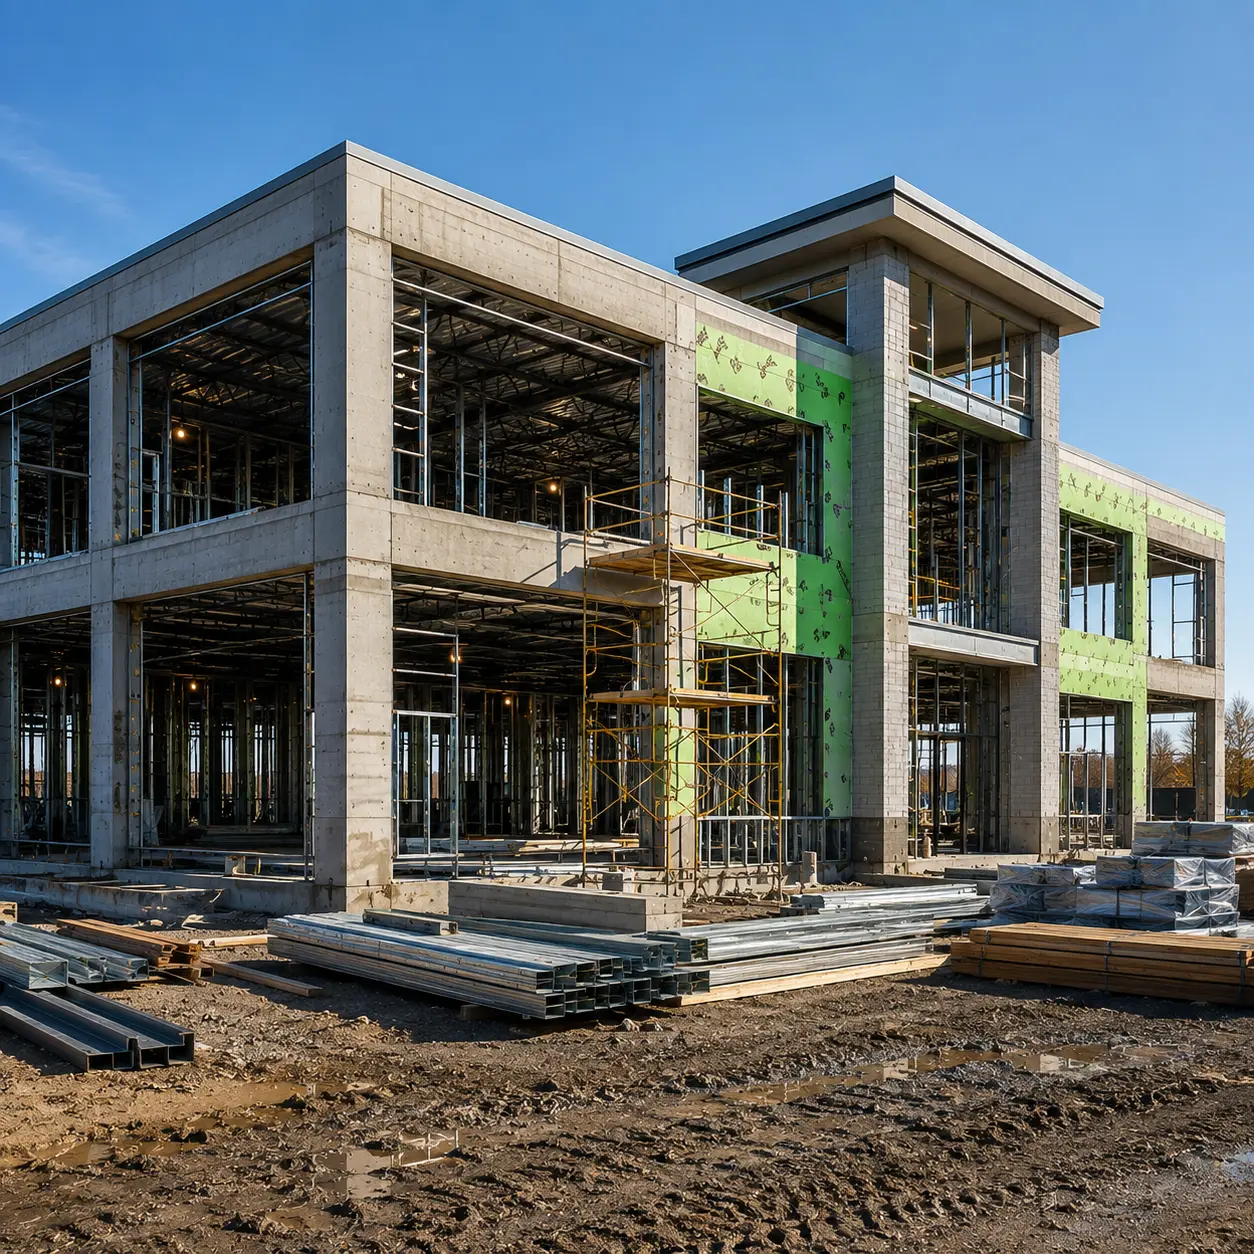
$6.5M
Mid-Construction Loan
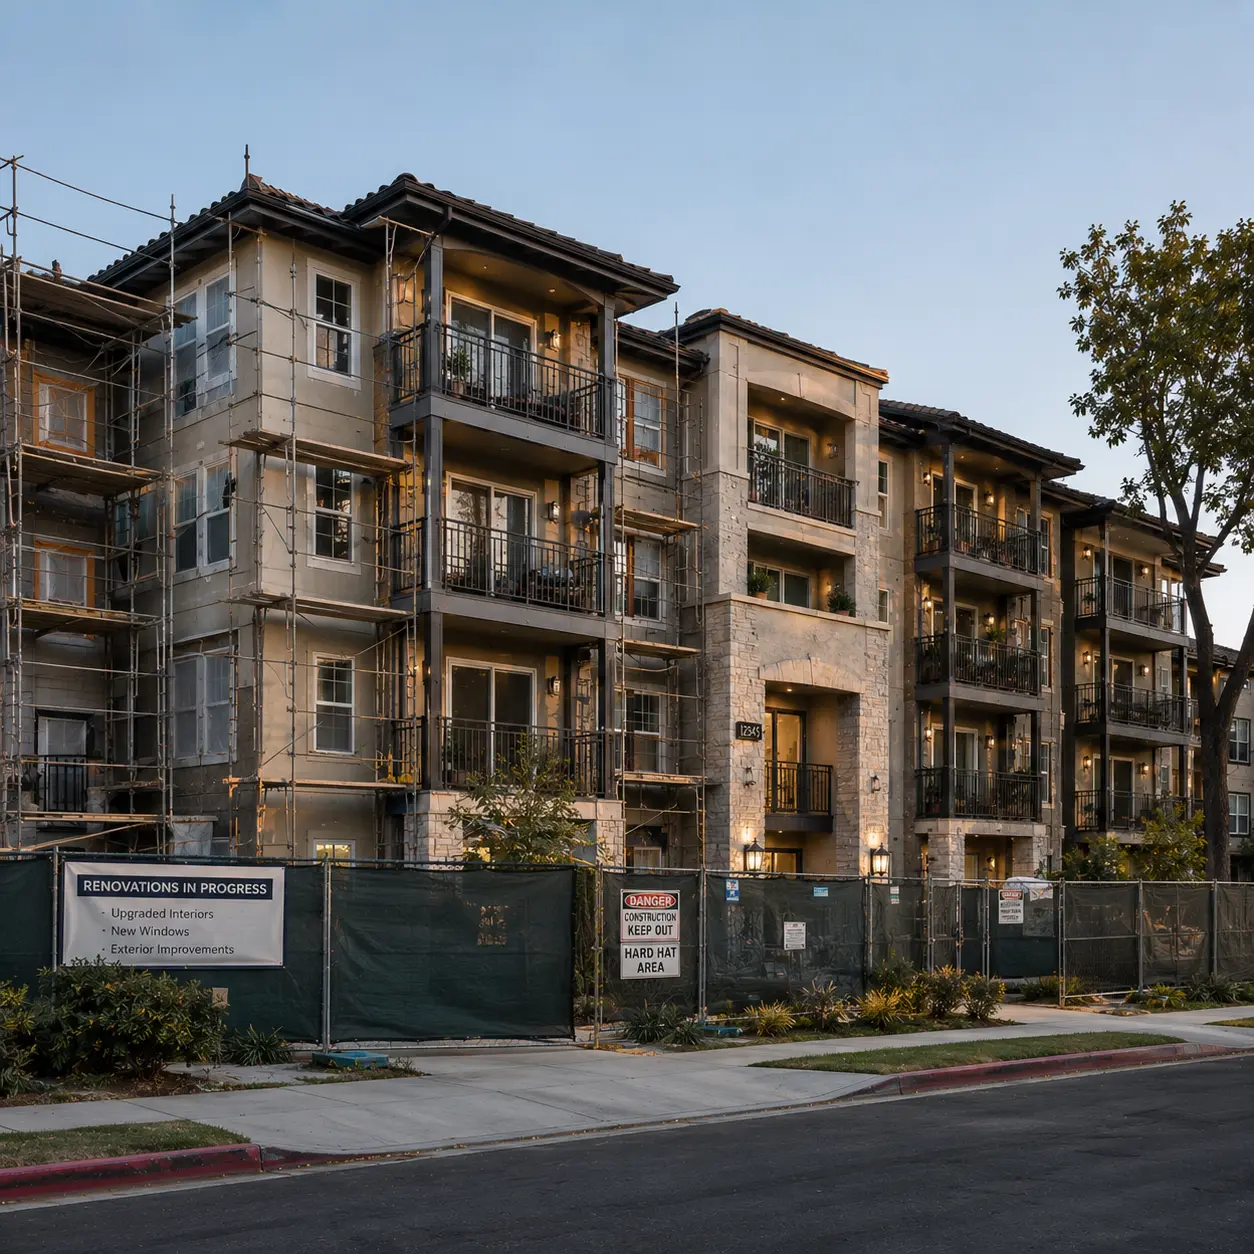
$8.95M
Multi-Family Bridge Loan

When the Asset Works, but the Financing Doesn’t
Multi-family and commercial transactions introduce more variables than smaller residential deals—more units, more tenants, layered income streams, regulatory considerations, and tighter execution windows.
As complexity increases, conventional lenders often struggle to keep pace. Committee reviews replace decision-making. Conditions multiply. Timelines stretch. Deals that still make sense stall—not because the asset failed, but because the financing model no longer fits the reality of the project.
These transactions often require apartment financing or commercial real estate loans that can move faster and adapt more easily than traditional bank programs.
Borrowers typically come to us when:
- A multi-family or commercial acquisition requires faster execution
- Existing debt needs to be refinanced or restructured
- Renovations or repositioning efforts require interim capital
- An asset needs time to stabilize before long-term financing
- Conventional underwriting can’t accommodate the deal structure or timeline
These are not broken deals. They’re deals that require flexible capital and decisive underwriting. That’s exactly what we offer.
What These Loans Are Designed to Do
Multi-family and commercial loans provide short-term capital for assets that need to move forward—not wait for rigid approval cycles.
They’re commonly used to:
- Acquire multi-family or commercial properties
- Refinance short-term or bank debt
- Fund renovations or repositioning strategies
- Carry an asset through lease-up or stabilization
- Bridge the gap to permanent financing or sale
This approach allows multi-family loans to be structured around real operating conditions, not static underwriting assumptions.
Why Builders Work With Insignia Capital
Direct Lender & Broker Flexibility
As both a direct lender and a capital markets partner, we’re able to structure financing across multiple channels, giving borrowers options rather than forcing a single solution.
Specialized Multi-Family & Commercial Focus
Our team focuses specifically on multi-family, mixed-use, and commercial assets, allowing us to evaluate deals based on how they actually operate—not generic credit models.
Speed & Reliability
LOIs and approvals move quickly, with closings often occurring within 10–14 business days, depending on structure and third-party requirements.
Capacity for Larger, More Complex Deals
We fund transactions from $500K up to $15M, supporting larger assets that exceed the limits of many conventional lenders.
Funding Options

Funding That Fits Your Deal
From quick flips to gap coverage, our loans deliver the capital you need when you need it. Let’s move your investment forward together.
Frequently Asked Questions
How We Take You From Application to Approval
When traditional lenders stall, we move. Our streamlined process takes you from application to approval in as few as five days—without the friction or surprises.
Why Investors Trust Insignia Capital
Fast Decisions
Traditional lenders measure timelines in weeks. We measure them in days, with average approvals in 48 hours and closings in as few as 5–7 business days. That speed doesn’t just save time. It keeps your project from falling apart before it even begins.
Flexible Structures
When you work with a big-box lender, you’re just another number in a long queue. The Insignia Capital Corp team is deliberately lean. Why? To ensure you receive the clarity and personal attention you deserve—without compromising the demands of the deal.
Direct Capital
Most lenders cap out when projects get big. Not Insignia. From $500K flips to $10M developments, we bring the capital and confidence your project demands.
Expert Credit Team
LLCs, unconventional assets, foreign income—these are the scenarios that confound conventional lenders. For us, they’re business as usual. We design loans around the deal, not a pre-generated checklist.
30+
Years Experience
1K+
Deals Closed
About Us
Meet the Insignia team, a deliberately small group of experts with three decades of experience and thousands of deals closed. When you work with us, you’ll actually know the people behind your loan. We listen, we problem-solve, and we pick up the phone. That’s why our clients trust us—and why they keep coming back.
