
Ground Up and
Mid-Construction Programs
Ground-up and mid-construction loans for single family homes, small lot sub-divisions and multi-family developments provide short-term capital for projects that are already in motion.
Rates from
9.25%
Loan from
$500K – $10M
Terms from
12-36 months
Up to
85% LTC
Funding Your Construction Loan
Construction projects don’t usually stall because the numbers don’t work. They stall when financing can’t keep up once the build is underway.
Insignia Capital Corp provides ground-up and mid-construction loans that step in when existing financing slows or stops. Our experienced sales and credit team is equipped to handle highly complex loan and entity structures, including boutique home builder loans and layered entity structures.
Loan Purpose
Terms
Property Type
SFR 1-4, small lot sub-division and multi-family
Loan amounts
$500K – $10M
LTV
90%
LTC
85%
LTARV up to
75%
Rates from
9.25%
Points
1.00% to 3.50%
Fees from
$1,995
Payments
Interest-only
Term
12-36 month
Prepay penalty
None or negotiable
Minimum credit score
640
Borrower entity required
No
Experience
Better pricing for pros

Case Study
Direct Single Family Residence
Funded Mid Construction Completion Luxury Loan
An experienced developer faced unexpected budget issues during the build of a luxury home, requiring a $4.8M loan to complete construction on an $8M projected value. Due to challenging market conditions, securing mid-construction financing was difficult. The developer approached Insignia Capital Corp for a sub-10% 18-month loan.
The Solution: $4.8M Bridge Loan
Insignia restructured the loan as a luxury fix-and-flip with a construction reserve holdback, reducing risk and extending the loan duration. This allowed the developer to complete the project and achieve a successful exit.
These loans provide funding to finish projects that exceed the original budget, often due to unforeseen costs or changes in scope. They are designed to ensure project completion when initial financing falls short.
$4.8M
Loan
18
Month Terms
$8M
Completion Value
10.000%
Rate
Recently Funded Transactions
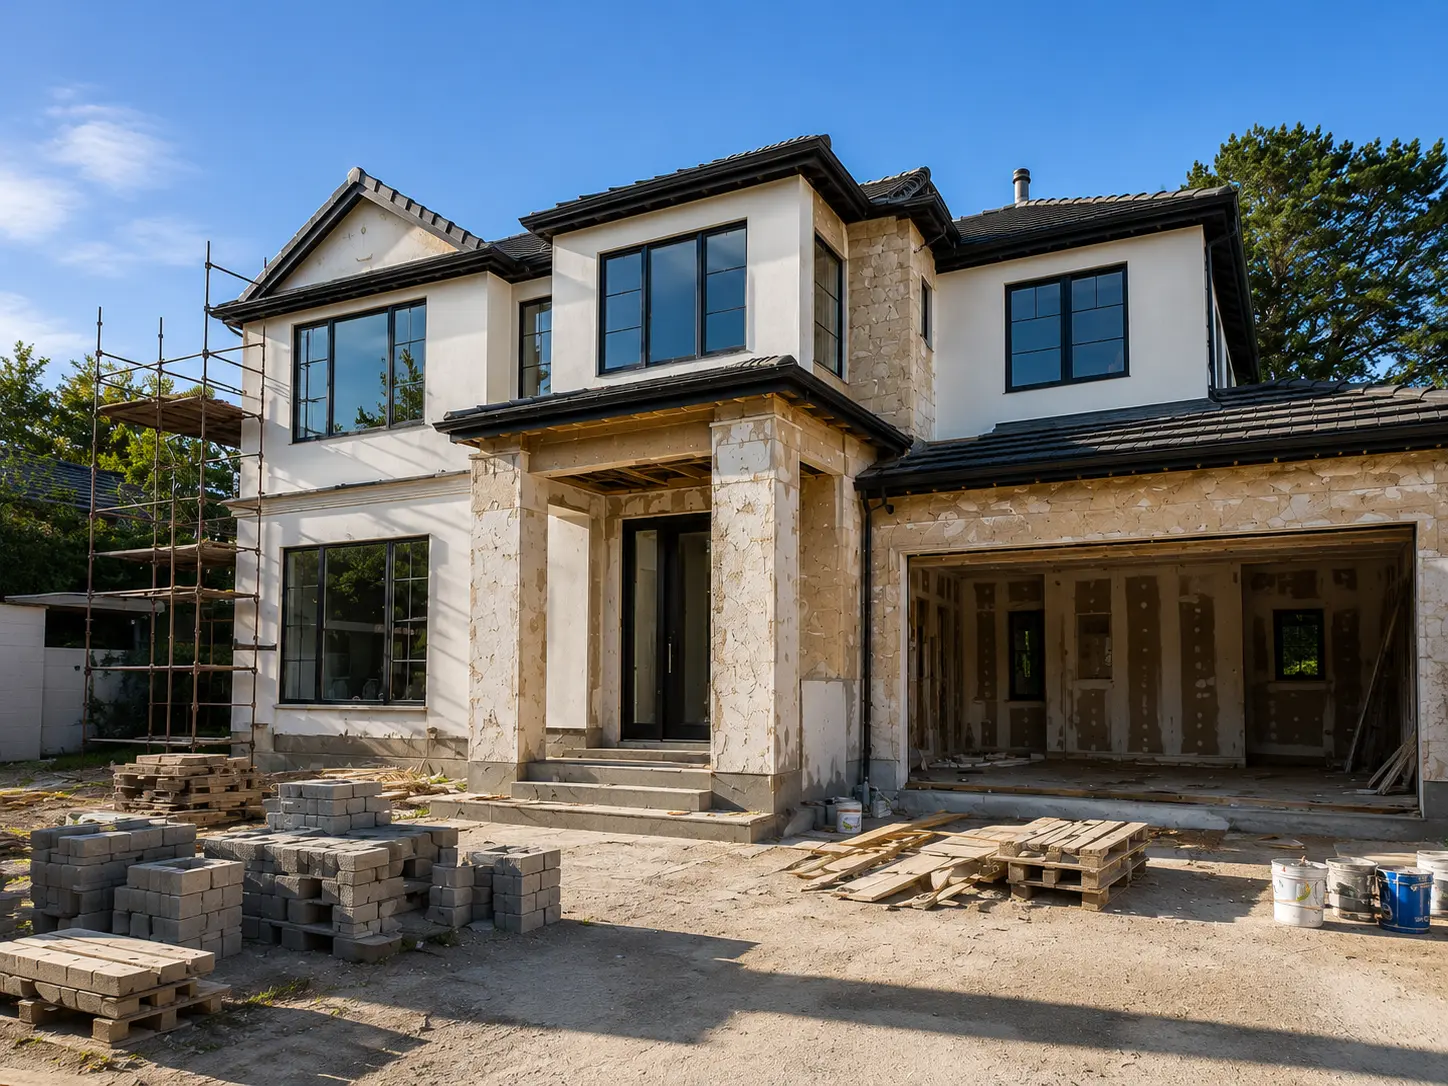
$4.95M
Single-Family Bridge Loan
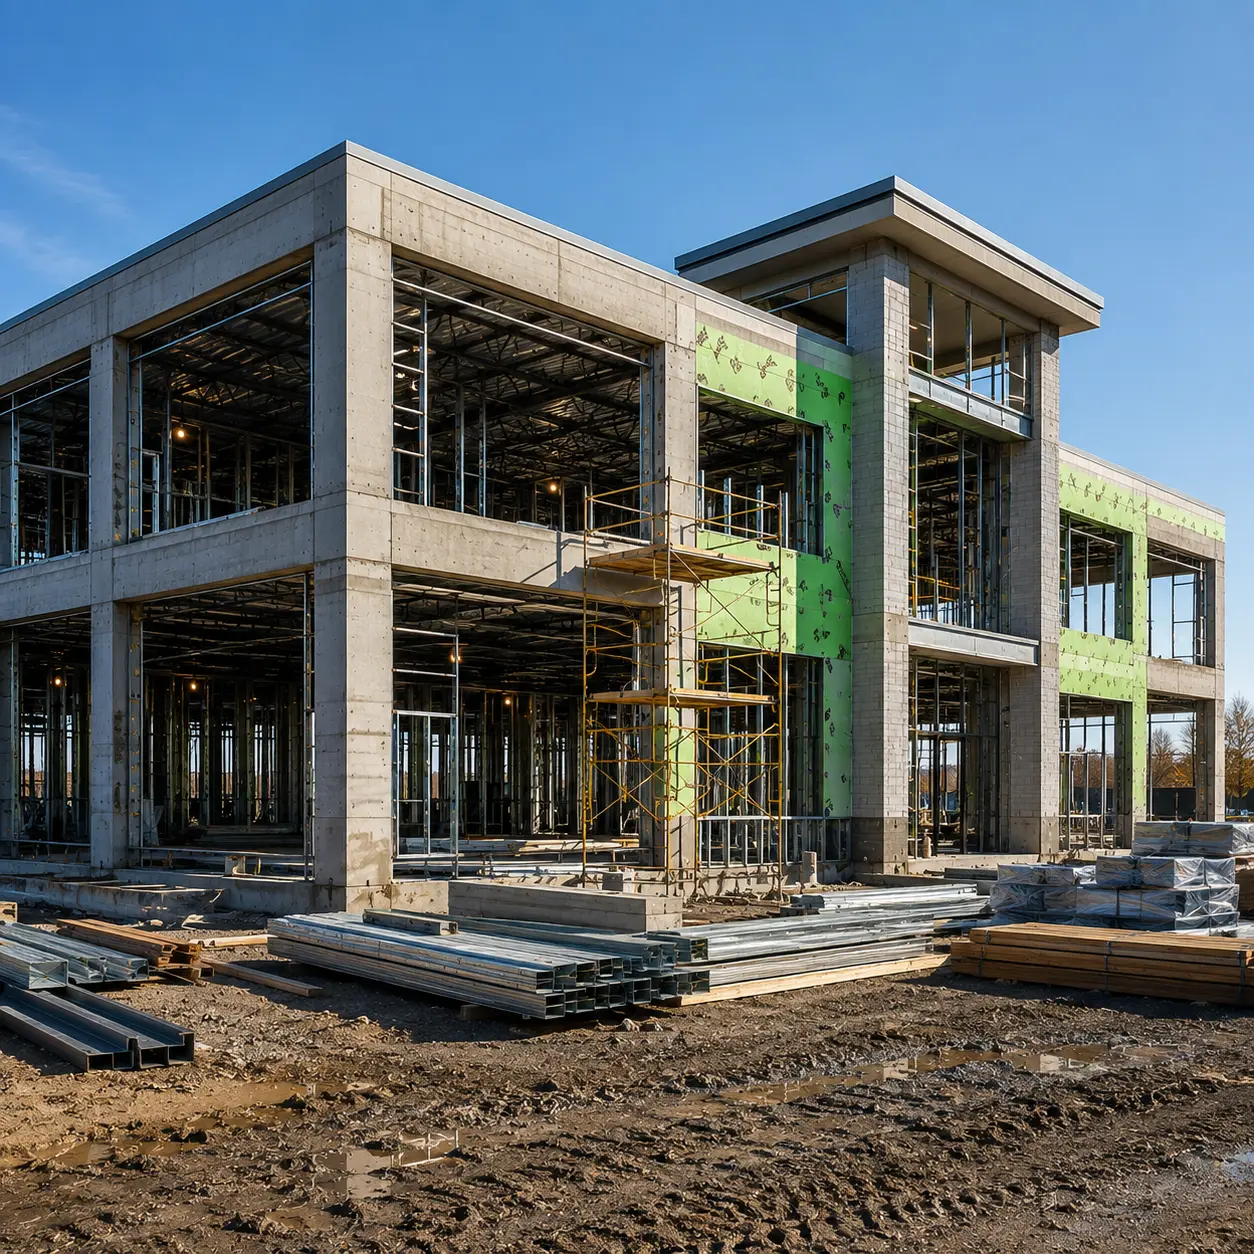
$6.5M
Mid-Construction Loan
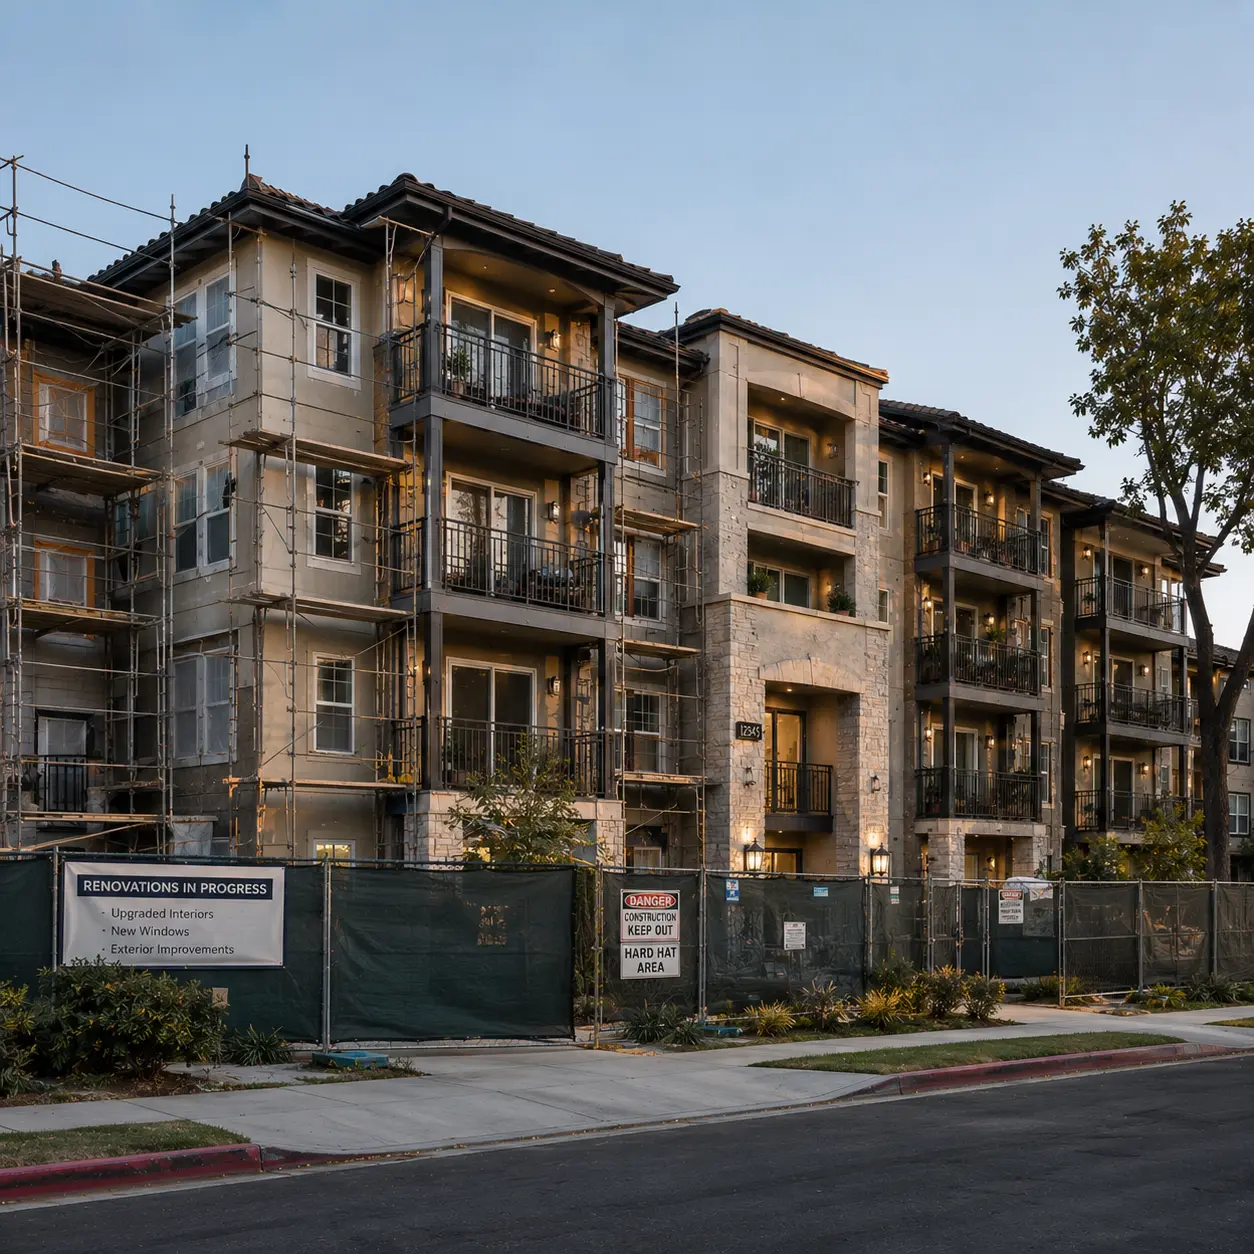
$8.95M
Multi-Family Bridge Loan

When the Project Still Works, But the Lender Doesn’t
Most mid-construction financing issues don’t start with a bad project. They start when the original lender stops matching the reality on the ground.
A bank that was comfortable at closing becomes cautious once timelines extend. Draws slow down. Conditions change. New requirements appear mid-build. Eventually, progress grinds to a halt—not because the project failed, but because the capital did.
Borrowers turn to us when:
- Construction costs have grown beyond the original budget
- Permitting or inspections have pushed the schedule out
- A lender pauses or exits partway through the build
- Additional funds are needed to reach completion or stabilization
What Mid-Construction Loans Are Designed to Do
Ground-up and mid-construction loans provide short-term capital for projects that are already in motion.
They’re commonly used to:
- Replace stalled construction financing
- Complete partially built projects
- Refinance existing construction debt
- Fund remaining work before sale or permanent financing
These loans are underwritten based on the current state of the build, not the original pro forma. The focus is on cost-to-complete, remaining scope, and a clear exit—not assumptions made months earlier.
Why Builders Work With Insignia Capital
If you’re mid-build, delays aren’t theoretical—they’re expensive. We exist to remove friction when timing matters most.
Direct Capital, Fewer Delays
We’re a direct lender. That means decisions are made internally, without broker layers or external committees slowing the process.
Construction-Focused Underwriting
Our credit team evaluates active projects the way builders do: remaining work, realistic timelines, contingency planning, and exit execution.
Speed When It Matters
Approvals and closings can occur in as little as 5–10 business days once documentation is complete—so construction doesn’t stay idle longer than necessary.
Capacity for Complex Projects
We fund ground-up and mid-construction loans from $500K up to $10M, supporting single-family builds, multifamily projects, and larger developments.
Funding Options

Funding That Fits Your Deal
From quick flips to gap coverage, our loans deliver the capital you need when you need it. Let’s move your investment forward together.
Frequently Asked Questions
How We Take You From Application to Approval
When traditional lenders stall, we move. Our streamlined process takes you from application to approval in as few as five days—without the friction or surprises.
Why Investors Trust Insignia Capital
Fast Decisions
Traditional lenders measure timelines in weeks. We measure them in days, with average approvals in 48 hours and closings in as few as 5–7 business days. That speed doesn’t just save time. It keeps your project from falling apart before it even begins.
Flexible Structures
When you work with a big-box lender, you’re just another number in a long queue. The Insignia Capital Corp team is deliberately lean. Why? To ensure you receive the clarity and personal attention you deserve—without compromising the demands of the deal.
Direct Capital
Most lenders cap out when projects get big. Not Insignia. From $500K flips to $10M developments, we bring the capital and confidence your project demands.
Expert Credit Team
LLCs, unconventional assets, foreign income—these are the scenarios that confound conventional lenders. For us, they’re business as usual. We design loans around the deal, not a pre-generated checklist.
30+
Years Experience
1K+
Deals Closed
About Us
Meet the Insignia team, a deliberately small group of experts with three decades of experience and thousands of deals closed. When you work with us, you’ll actually know the people behind your loan. We listen, we problem-solve, and we pick up the phone. That’s why our clients trust us—and why they keep coming back.
